As of 29 October 2026 (12 Kartik 2083). Product terms and interest rates are as listed on the banks’ own websites on 29 October 2026 (Global IME, NMB, Nepal Bank, Machhapuchchhre, NIC Asia and Everest; Global IME’s rate sheet and the others are effective from 1 Kartik 2083, 18 October 2026). The legal points are from the National Civil Code 2074, the Act Relating to Children 2075 and the Income Tax Act 2058 as read on the nepallaws.com mirror and the FAOLEX copy, because the Law Commission’s PDF server was not reachable from a script. The NRB rule on NID-based account opening is as reported by Sharesansar on 9 January 2025. Nabil Bank’s child product page could not be located on its site. Rates change every month; check the bank’s sheet before you sign.
Tihar is when most Nepali children receive their biggest pile of cash all year, and a minor bank account Nepal banks call a “Balbalika Bachat Khata” is the simplest place to park that money. A minor account is an ordinary savings account opened in the child’s name but operated by a parent or guardian until the child turns 18. This guide covers who can open one, which documents the bank will ask for, what the accounts pay today, how interest is taxed and what happens when the child becomes an adult.
Quick answers
| Question | Answer (checked 29 October 2026) |
|---|---|
| Who counts as a minor | A child who has not completed 18 years (Civil Code 2074, section 2(e); Children’s Act 2075, section 2(j)) |
| Who operates the account | The parent or legal guardian, until the child turns 18 |
| Core documents | Child’s birth certificate, guardian’s citizenship or passport, guardian’s NID, photos of both |
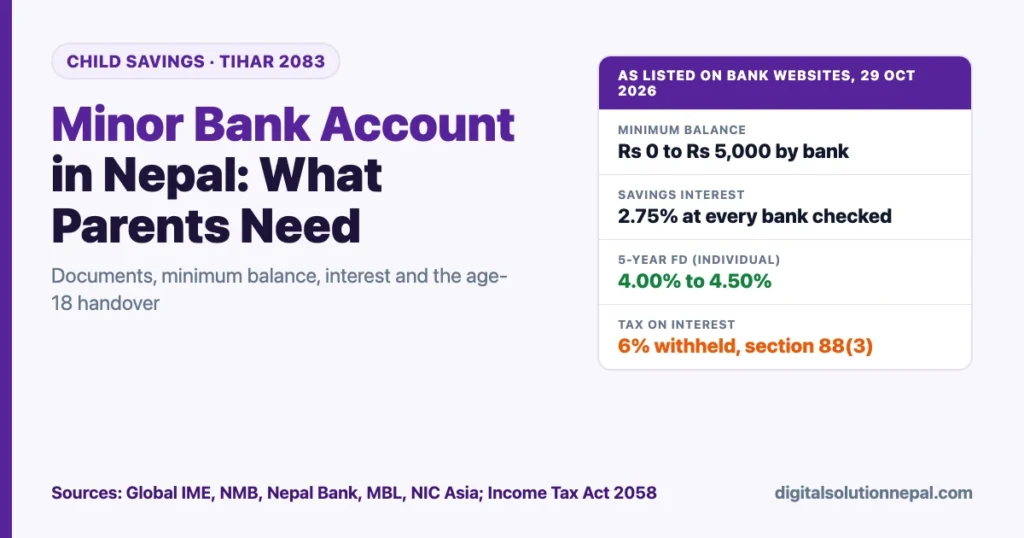
| Typical minimum balance | Rs 0 at Nepal Bank and Machhapuchchhre; Rs 1,000 at Global IME; Rs 5,000 at NMB (Jeevan Chakra) |
| Interest on child savings today | 2.75% a year at every bank we checked |
| Better rate for long-term money | 5-year individual fixed deposits: 4.00% to 4.50% at the banks checked |
| Tax on interest | 6% deducted by the bank on interest paid to a natural person (Income Tax Act section 88(3)) |
| At 18 | Account converts to a normal savings account or is closed and re-opened in the child’s own name |
What a minor bank account in Nepal actually is
Nepali law draws the adult line at 18. Section 2(e) of the National Civil Code 2074 (मुलुकी देवानी संहिता) defines a minor as a child who has not attained eighteen years of age, and section 2(j) of the Act Relating to Children 2075 (बालबालिका सम्बन्धी ऐन) uses the same threshold. A person below that age cannot sign a binding account contract on their own, so the account is opened in the child’s name and a guardian signs the mandate and does the transacting.
The Civil Code also tells the guardian how to behave with the child’s money. Section 143 says the guardian must supervise and protect the property of the person under guardianship, and may invest it in a business or transaction. Section 144 requires the guardian to keep accurate books and accounts and to hand those accounts, with an inventory of the property, to the ward within one year of the ward reaching majority. Our reading: a child account with regular statements is the easiest way to meet that record-keeping duty, and the money in it belongs to the child, not to the parent.
Banks package these accounts under names like Balbalika Bachat Khata (बालबालिका बचत खाता) or as a life-stage product. Machhapuchchhre Bank, for example, states that its Balbalika account can be opened only in the name of a minor below 18, and NMB Bank’s Jeevan Chakra product has a “Balapan” stage for newborns to 12-year-olds and a “Joshila Haath” stage for 13 to 18.
Documents the bank will ask for
The exact list varies by bank, but the pattern is the same across the four document lists we read (Nepal Bank, Machhapuchchhre, Everest and NMB):
- Account opening form and KYC form filled in by the guardian, with the child’s details and the guardian’s details.
- Proof of the child’s date of birth. A birth certificate (जन्म दर्ता प्रमाणपत्र) from the ward office is standard. Machhapuchchhre also accepts a passport or a minor identity card, and Everest Bank accepts a “minor identification letter”. If your child’s certificate is missing or has errors, read our guide on whether a birth certificate can be downloaded online in Nepal before you go to the bank.
- Guardian’s identity. Citizenship certificate is the usual document; a valid passport, voter card or driving licence is accepted by Everest and Machhapuchchhre.
- Guardian’s National Identity Card. Nepal Bank lists the NID as mandatory. Machhapuchchhre says a deferral may be allowed with bank approval. Sharesansar reported on 9 January 2025 that Nepal Rastra Bank directed banks to open accounts based on National Identity Card details from 1 Magh 2081, so expect every bank to ask for the guardian’s NID or NID number.
- Photographs. Two recent passport-size photos of both the child and the guardian (Machhapuchchhre’s list); other banks ask for one or two.
- Extras some banks want. Nepal Bank asks for a recommendation letter from the local authority and a proof of the guardian’s current address such as an electricity or telephone bill.
Keep the originals with you. Everest Bank’s documentation page says original documents must be shown for verification.
If you already bank with Nabil, Siddhartha or another bank that supports Nagarik App onboarding, see how to open a bank account by scanning a QR from the Nagarik App. That route is for adults with citizenship; a child account still needs the guardian at the counter or on a video call.
Child savings accounts compared
All figures are as listed on each bank’s website on 29 October 2026.
| Bank and product | Minimum balance | Interest (a year) | Notable terms |
|---|---|---|---|
| Nepal Bank, Balbalika Bachat Khata | Rs 0 | 2.75% | No cheque book or Visa card; closed and re-opened as a new account at 18 or when citizenship is presented |
| Machhapuchchhre Bank, MBL Balbalika Bachat Khata | Rs 0 | 2.75% | Free first cheque book; mobile and internet banking operated by the guardian; auto-converts to a normal savings account at majority; fees waived first year only |
| Global IME Bank, Global Balbalika Bachat | Rs 1,000 | 2.75% | Cheque book, Visa debit card, mobile and internet banking on demand; automatic fixed deposit conversion for balances above Rs 50,000 |
| NMB Bank, Jeevan Chakra (Balapan 0 to 12, Joshila Haath 13 to 18) | Rs 5,000 | 2.75% | Daily balance, quarterly interest posting; locker, SIP link and demat facilities listed |
| NIC Asia Bank | No child-specific product listed | 2.75% on “all other savings” | Sathi Bachat Khata pays 3.25% but needs Rs 100,000 minimum |
Three things stand out. First, the rate is the same everywhere: 2.75% is the floor savings rate at every bank in the table, so the choice comes down to minimum balance, fees and features. Second, Nepal Bank’s product deliberately has no card or cheque book, which some parents prefer because the money cannot be spent casually. Third, Global IME’s automatic sweep into a fixed deposit above Rs 50,000 is the only built-in “earn more” feature we found; at the other banks you must open the fixed deposit yourself.
Nabil Bank launched an app-based “Gen Alpha” children’s account in September 2022, according to Sharesansar’s report at the time, but we could not find a current product page on nabilbank.com on 29 October 2026, so it is not in the table. Global IME also runs a “Global Junior” app for 12 to 17-year-olds linked to the parent’s account, reported by Sharesansar in September 2024.
Interest rates and the fixed deposit option for education savings
A savings rate of 2.75% is low by Nepali standards of a few years ago. For money the child will not need for years, a fixed deposit in the child’s name pays more:
| Bank | Individual FD, 5 years and above | Individual FD, 3 to below 5 years |
|---|---|---|
| NMB Bank | 4.50% | 3.50% |
| Global IME Bank | 4.00% | 3.50% |
| NIC Asia Bank | 4.00% | 3.01% (above 2 to below 5 years) |
Our calculation: Rs 50,000 of Tihar money left in a 2.75% savings account for five years grows by about Rs 7,260 with annual compounding; the same amount in a 5-year fixed deposit at 4.50% grows by about Rs 12,300. The difference is small in rupees but it compounds, and an education fund built from yearly Dashain and Tihar gifts in fixed deposits is a realistic way to cover a first year of college. Rules on early withdrawal, renewal and tax are in our guide to fixed deposits in Nepal.
Two practical warnings. Banks revise deposit rates every month; the sheets we read are all effective 1 Kartik 2083, and the November sheets will be out by the time you read this. And a fixed deposit in a minor’s name is still the child’s property under the Civil Code, so the guardian should treat it as such when the child turns 18.
Tax on a child’s interest
Section 88(3) of the Income Tax Act 2058 (आयकर ऐन) requires a resident bank or financial institution to withhold tax at 6% on interest paid to any natural person on deposits where the interest has a source in Nepal and is not connected with a business. The nepallaws.com text notes the 6% sub-section was inserted by the Finance Act 2080, and Pradhan and Associates’ briefing on the Finance Act 2083 lists 6% for deposit interest for fiscal year 2083/84.
The bank deducts the tax before crediting interest, so a child earning Rs 1,375 of interest on Rs 50,000 at 2.75% receives Rs 1,292.50 after Rs 82.50 of tax, our calculation. Section 92 of the Act lists bank deposit interest covered by section 88(3) among payments from which tax is withheld finally; our reading is that nothing further is due or filed for a child’s savings interest, and that a child’s deposit interest is not added to a parent’s salary income. We found no separate tax rule for minors’ bank interest in the Act.
Note that an older rate of 5% still appears on many websites. The Act text we read and the 2083/84 briefing both say 6%.
Steps to open a minor bank account in Nepal
- Pick the bank by minimum balance and features using the table above. If the child already has school fees or an existing family relationship at one bank, that usually wins.
- Get the child’s birth certificate from the ward office if you do not have it, and check that the name spelling matches the guardian’s citizenship.
- Carry the guardian’s citizenship certificate, NID card or NID number, two photos each of the child and the guardian, and a utility bill if the bank asks for address proof.
- Fill in the account opening form and KYC form at the branch, signing as guardian. The child’s name goes on the account; the guardian’s signature is the operating mandate.
- Deposit the opening amount (Rs 0 to Rs 5,000 depending on the bank) and ask for a passbook or statement access.
- Decide at the counter whether you want a debit card, mobile banking or a cheque book. At Nepal Bank these are not issued; at Machhapuchchhre and Global IME they are on request.
- If the balance will sit untouched, ask about a fixed deposit in the child’s name or Global IME’s automatic sweep.
- Keep a simple record of deposits and withdrawals. The Civil Code’s section 144 duty to maintain accounts applies to guardians, and the statement does most of the work.
What happens when the child turns 18
The guardian’s authority ends at majority. Banks handle the conversion in two ways. Machhapuchchhre states the account is automatically converted to a normal savings account once the holder legally attains majority. Nepal Bank states that after the holder reaches 18 or presents a citizenship certificate, the minor account is closed, a new account is opened according to the holder’s wishes and the balance is transferred.
Either way the young adult must visit the bank with their own citizenship certificate and NID to complete KYC in their own name. If nobody does this, the account can sit without a valid mandate and eventually become dormant; our guide to dormant bank accounts in Nepal explains the reactivation process and charges. Our reading: put a reminder in the calendar for the child’s 18th birthday and go within a month.
Nepal-specific tips for parents
- Use the account for Tihar and Dashain gift money, scholarship payments and relatives’ remittance gifts. Having a bank record of where the money came from avoids questions later.
- Gift money is not taxable income for a child in any rule we found, but interest is taxed at 6% as described above.
- Do not open the account purely to park the parent’s own money. Under the Civil Code the balance belongs to the child, and withdrawing it for household expenses can be challenged once the child is an adult.
- Register the guardian’s mobile number for SMS alerts. NRB’s circular reported in January 2025 also requires banks to verify that the mobile number belongs to the person registering it.
- If both parents want access, ask the bank whether a second guardian can be recorded; Machhapuchchhre’s page refers to “the authorized guardian” in the singular, so check before assuming.
Need help with the bank forms or a birth certificate?
Digital Solution, Pokhara prepares and scans documents, helps families fill account opening and KYC forms, and guides you through ward-office paperwork such as birth certificate corrections. बच्चाको खाता खोल्न चाहिने कागजात मिलाउन हामीलाई सम्झनुहोस्।
Frequently asked questions
Can a grandparent or uncle open a minor bank account in Nepal?
The guardian is normally the father or mother. A grandparent or other relative needs legal guardianship under Chapter 6 of the Civil Code 2074, and the bank will ask for proof. Ask the branch before gathering documents.
Is a birth certificate compulsory?
Every list we read asks for proof of the child’s date of birth, and a ward-office birth certificate is the standard document. Machhapuchchhre also accepts a passport or minor identity card, and Everest Bank accepts a minor identification letter.
What interest does a child savings account earn in Nepal?
On 29 October 2026 every child or general savings product we checked paid 2.75% a year. Five-year individual fixed deposits paid 4.00% to 4.50% at NMB, Global IME and NIC Asia.
Is a child’s bank interest taxed?
Yes. The bank withholds 6% under section 88(3) of the Income Tax Act 2058 before crediting interest. Section 92 treats it as a final withholding, our reading, so no return is needed for the child.
Can the child withdraw money or use a card?
Until 18 the guardian operates the account. Some banks issue a debit card or mobile banking on request, operated by the guardian; Nepal Bank issues neither on its Balbalika account.
What happens to the account at 18?
It converts to a normal savings account (Machhapuchchhre) or is closed and re-opened in the young adult’s own name with the balance transferred (Nepal Bank). The new adult must complete KYC with their own citizenship and NID.
Conclusion
A minor bank account Nepal parents open this Tihar will earn 2.75% at every bank we checked, so pick on minimum balance and features: Rs 0 at Nepal Bank and Machhapuchchhre, Rs 1,000 at Global IME, Rs 5,000 for NMB’s life-stage product. Bring the child’s birth certificate and the guardian’s citizenship and NID, expect 6% tax to come off the interest, move long-term money into a 4% to 4.5% five-year fixed deposit, and diary the 18th birthday so the account passes cleanly into the child’s own hands.
Sources
- Nepal Laws mirror, National Civil (Code) Act 2074, section 2 definitions (minor): https://nepallaws.com/Laws/the-national-civil-code-act-2074/part-1-preliminary/chapter-1-general-provisions/section-2-definitions/
- Nepal Laws mirror, Civil Code 2074, section 143 (guardian to manage ward’s property): https://nepallaws.com/Laws/the-national-civil-code-act-2074/part-3-family-law/chapter-6-provisions-relating-to-guardianship/section-143-property-to-be-supervised-protected-and-managed-properly/
- Nepal Laws mirror, Civil Code 2074, section 144 (guardian must maintain accounts): https://nepallaws.com/Laws/the-national-civil-code-act-2074/part-3-family-law/chapter-6-provisions-relating-to-guardianship/section-144-to-maintain-books-and-accounts-accurately/
- FAOLEX copy, Act Relating to Children 2075, section 2(j): https://faolex.fao.org/docs/pdf/nep209414.pdf
- Nepal Laws mirror, Income Tax Act 2058, section 88 (withholding on investment returns): https://nepallaws.com/Laws/income-tax-act-2058-2002/chapter-17-withholding-on-payment/section-88-withholding-of-tax-in-making-payment-for-investment-return-and-service-charge/
- Nepal Laws mirror, Income Tax Act 2058, section 92 (final withholding): https://nepallaws.com/Laws/income-tax-act-2058-2002/chapter-17-withholding-on-payment/section-92-payment-from-which-tax-is-withheld-finally/
- Pradhan and Associates, Client Briefing, Income Tax Rates 2083-84 (2026): https://pradhanlaw.com/file-upload/files/P&A%20Client%20Briefing%20-%20Income%20Tax%20Rates%202083-84%20(2026-27%20AD).pdf
- Global IME Bank, Global Balbalika Bachat product page (read 29 October 2026): https://www.globalimebank.com/products/saving-deposits/global-balbalika-bachat/
- Global IME Bank, interest rates effective 18 October 2026: https://www.globalimebank.com/interest-rates/
- NMB Bank, NMB Jeevan Chakra product page: https://www.nmb.com.np/en/products/saving-accounts/individual/nmb-jeevan-chakra
- NMB Bank, interest rate effective 18 October 2026: https://www.nmb.com.np/en/interest-rate
- Nepal Bank, Balbalika Bachat Khata: https://nepalbank.com.np/personal/products/saving-account/balbalika-bachat-khata
- Nepal Bank, interest rates on deposits effective Kartik 1, 2083: https://nepalbank.com.np/personal/interest-rate/interest-rates-on-deposits
- Machhapuchchhre Bank, MBL Balbalika Bachat Khata: https://www.machbank.com/products/saving-deposits/mbl-balbalika-bachat-khata/
- Machhapuchchhre Bank, deposit interest rate effective 18 October 2026: https://www.machbank.com/deposit-interest-rate/
- NIC Asia Bank, savings products and interest rates effective 1 Kartik 2083: https://www.nicasiabank.com/savings/ and https://www.nicasiabank.com/interest-rates/
- Everest Bank, personal account opening documentation: https://everestbankltd.com/supports/how-do-i/account-opening-documentation/personal-account/
- Sharesansar, National Identity Card mandatory for opening bank accounts from Magh 1 (9 January 2025): https://www.sharesansar.com/newsdetail/national-identity-card-mandatory-for-opening-bank-accounts-from-magh-1-2025-01-09
- Sharesansar, Nabil Bank launches Gen Alpha saving account (15 September 2022): https://www.sharesansar.com/newsdetail/nabil-bank-launches-mobile-app-based-gen-alpha-saving-account-teach-your-kids-to-develop-saving-habits-and-gain-some-financial-awareness-with-fun-2022-09-15
- Sharesansar, Global IME Bank launches Global Junior app for teens (3 September 2024): https://www.sharesansar.com/newsdetail/global-ime-bank-launches-innovative-financial-app-for-teens-2024-09-03
This article is general information checked on 29 October 2026, not financial or legal advice; bank terms and rates change, so confirm with the branch before opening an account.

Rabin Paudel
Rabin Paudel is the Founder of Digital Solution, a Content Creator, and an AI Trainer. He shares practical and easy-to-understand content on Artificial Intelligence, Digital Literacy, Online Services, FinTech, and Technology. His mission is to make technology simple, accessible, and useful for everyone.
View all posts by Rabin Paudel →