As of 28 October 2026 (11 Kartik 2083). Every figure on this page is from the Inland Revenue Department’s rate sheet titled “Tax rates applicable to natural persons under the Income Tax Act, 2058 (for income year 2083/084)”. Worked figures labelled “our calculation” are ours. This is general information, not tax advice for your case.
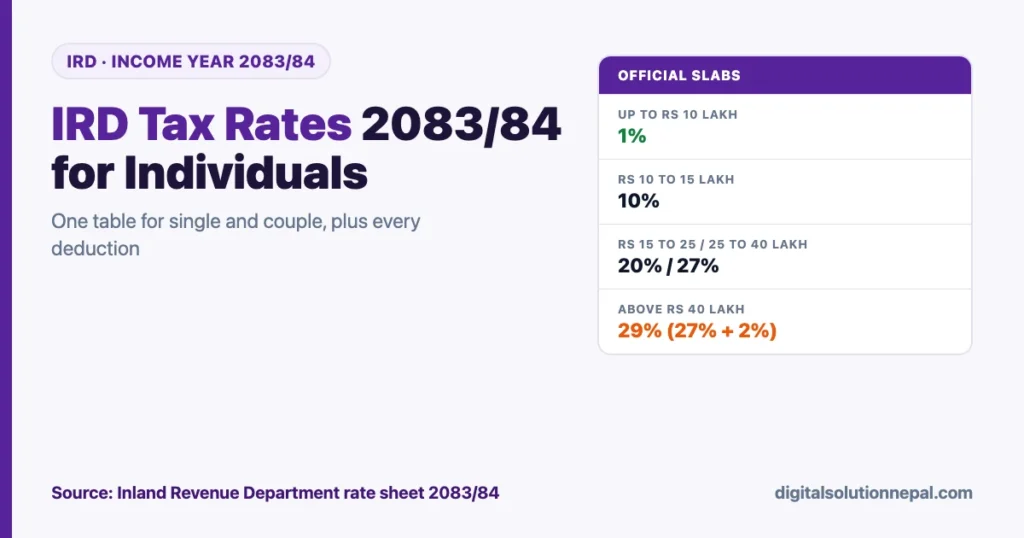
The Inland Revenue Department (IRD, आन्तरिक राजस्व विभाग) has published its official IRD tax rates 2083/84 sheet for natural persons. It confirms the biggest change in years: one slab table for everyone, with no separate rates for married couples, and a first band that now runs to Rs 10 lakh.
The sheet is also the clearest single list of everything else an individual taxpayer needs: deductions, the fixed presumptive tax for small businesses, turnover tax rates, capital gains tax, the 5% tax on foreign-currency income such as YouTube earnings, and the yearly tax on hired vehicles. This guide puts all of it in English, in order.
The 2083/84 income tax slabs
The same table applies to a single person and to a couple. Here is IRD’s table, with tax at each band calculated for a taxable income of Rs 60 lakh, as IRD’s own sheet shows.
| Band | Taxable income | Rate | Tax in this band at Rs 60 lakh income |
|---|---|---|---|
| 1 | Up to Rs 10,00,000 | 1% | Rs 10,000 |
| 2 | Rs 10,00,001 to Rs 15,00,000 | 10% | Rs 50,000 |
| 3 | Rs 15,00,001 to Rs 25,00,000 | 20% | Rs 2,00,000 |
| 4 | Rs 25,00,001 to Rs 40,00,000 | 27% | Rs 4,05,000 |
| 5 | Above Rs 40,00,000 | 29% (27% + 2% additional tax) | Rs 5,80,000 |
| Total tax on Rs 60 lakh | Rs 12,45,000 |
The 29% rate is written in the sheet as the 27% rate plus an additional 2 percentage points on income above Rs 40 lakh.
Who does not pay the 1% band
According to the sheet, the 1% tax in band 1 does not apply to:
- taxpayers registered as a sole proprietorship firm,
- pension income, and
- individuals who contribute to a pension fund and the contribution-based Social Security Fund (SSF).
This is from Schedule 1, section 1, sub-sections (1) and (2) of the Income Tax Act. For those people, the first Rs 10 lakh carries no tax, a saving of up to Rs 10,000 a year (our calculation).
For worked salary examples and a comparison with last year’s slabs, see our income tax rates 2083/84 guide.
Deductions and rebates you can claim
IRD lists these amounts as either excluded from income or allowed as a deduction or rebate.
| # | What | How much you can claim |
|---|---|---|
| 1 | Contribution to an approved retirement fund | Up to Rs 5 lakh or one-third of assessable income, whichever is lower |
| 2 | Remote area allowance | Class A Rs 50,000; B Rs 40,000; C Rs 30,000; D Rs 20,000; E Rs 10,000 |
| 3 | Foreign allowance for staff of Nepal’s diplomatic missions abroad | 75% of the allowance |
| 4 | Resident with pension income | An extra 25% of the exemption limit |
| 5 | Resident person with a disability | An extra 50% of the exemption limit |
| 6 | Investment (life) insurance premium | Premium paid or Rs 40,000, whichever is lower |
| 7 | Health insurance with a resident insurer | Premium paid or Rs 20,000, whichever is lower |
| 8 | Insurance of your own private building with a resident insurer | Premium paid or Rs 10,000, whichever is lower |
| 9 | Tuition fees paid to a resident person for your children’s education | 25% of the fees or Rs 25,000, whichever is lower |
| 10 | Women whose only income is remuneration | 10% rebate on the tax payable |
| 11 | Approved medical expenses, by bills | Tax credit of 15% of actual cost or Rs 750, whichever is lower |
What these mean in practice
- Pension and disability: the sheet says these are a percentage of the limit you get exemption on. Read against band 1 of Rs 10 lakh, that is Rs 2.5 lakh extra for pension income and Rs 5 lakh extra for a person with a disability (our reading and calculation; confirm with your tax office).
- Children’s tuition fees: if you paid Rs 1,50,000 in school fees in the year, 25% is Rs 37,500, so the deduction is capped at Rs 25,000 (our calculation). If you paid Rs 80,000, the deduction is Rs 20,000.
- Women’s 10% rebate: it is a cut in the tax amount, not in income. A woman with only salary income and a tax bill of Rs 60,000 pays Rs 54,000 (our calculation).
- Medical expenses: this is a tax credit, so it reduces tax directly, but the maximum is small at Rs 750.
Want every deduction claimed on your tax?
Digital Solution helps individuals and small businesses work out tax, file D-01 and D-02 returns and claim deductions like insurance and children’s tuition fees. Message us on WhatsApp.
Presumptive tax for small businesses (D-01 return)
Resident individuals whose taxable business income is up to Rs 3 lakh and whose yearly turnover is not more than Rs 30 lakh pay a fixed tax, under section 4(4) of the Income Tax Act. They file the D-01 return.
| Where the business operates | Tax for 2083/84 |
|---|---|
| Metropolitan or sub-metropolitan city | Rs 7,500 |
| Municipality | Rs 4,000 |
| Any other area | Rs 2,500 |
Turnover tax (D-02 return)
Turnover tax is for resident individuals with Nepal-source business income only, taxable business income up to Rs 10 lakh, and turnover above Rs 30 lakh up to Rs 1 crore. It does not apply to income from consultancy and specialist services of professionals such as doctors and engineers. This is section 4(4ka) of the Act.
The tax is the total of the parts below that apply to your turnover.
Part (a): turnover up to Rs 30 lakh
| Where the business operates | Tax |
|---|---|
| Metropolitan or sub-metropolitan city | Rs 7,500 |
| Municipality | Rs 4,000 |
| Any other area | Rs 2,500 |
Parts (b) and (c): turnover above Rs 30 lakh
| Type of business | Rs 30 lakh to Rs 50 lakh | Rs 50 lakh to Rs 1 crore |
|---|---|---|
| Goods such as gas and cigarettes sold with up to 3% commission or value added | 0.25% | 0.3% |
| Other goods businesses | 1% | 0.8% |
| Service businesses | 2% | 2% |
Example (our calculation, our reading of how the parts add up): a grocery shop in a sub-metropolitan city with Rs 45 lakh turnover pays Rs 7,500 for the first Rs 30 lakh plus 1% on the next Rs 15 lakh (Rs 15,000), a total of Rs 22,500. Check the exact computation with your tax office or in the D-02 form.
When to pay turnover tax
Under section 94(1ka), turnover tax is paid in two instalments.
| Deadline | What to pay |
|---|---|
| End of Poush | Tax at the set rate on turnover up to Poush 20 |
| End of Asar | Tax on the estimated full-year turnover (actual to Asar 20 plus estimate to month-end), minus what was paid by the end of Poush |
Non-residents
A non-resident natural person pays tax at a flat 25% on taxable income for the year.
Capital gains tax for resident individuals
| What you sell | Ownership period | Rate |
|---|---|---|
| Non-business land or house and land | 5 years or more | 7.5% |
| Non-business land or house and land | Less than 5 years | 10% |
| Shares in entities listed with the Securities Board of Nepal | More than 365 days | 7.5% |
| Shares in entities listed with the Securities Board of Nepal | 365 days or less | 10% |
Our guides to share capital gains tax and land and house capital gains tax explain how the gain is worked out.
5% tax on foreign-currency income (YouTube, freelancing, software)
For resident individuals not running a registered business, IRD’s sheet sets a 5% tax, deducted by the bank, financial institution or money transfer company when it pays out, on foreign-currency payments received for:
- providing software or similar electronic services outside Nepal (section 95ka, sub-section 6kha),
- providing consultancy services outside Nepal in a personal capacity (sub-section 6ga), and
- uploading audio-visual content on social media (sub-section 6gha), which covers YouTube and similar platforms.
So when your YouTube or freelance payment lands through a Nepali bank or remittance company, expect 5% to be withheld. See our guides on YouTube monetization in Nepal and the TDS rates guide for how withholding works.
Yearly income tax on hired vehicles
Owners of vehicles used for hire pay a yearly income tax through the Transport Management Office at registration or renewal.
| Vehicle | Yearly tax per vehicle |
|---|---|
| Car, jeep, van, microbus up to 1,300 cc | Rs 6,500 |
| 1,301 to 2,000 cc | Rs 7,000 |
| 2,001 to 2,900 cc | Rs 7,500 |
| 2,901 to 4,000 cc | Rs 9,500 |
| Above 4,000 cc | Rs 11,000 |
| Mini truck, minibus, water tanker | Rs 9,500 |
| Mini tipper | Rs 11,000 |
| Truck, bus | Rs 12,500 |
| Dozer, excavator, loader, roller, crane and similar machinery | Rs 17,500 |
| Oil tanker, gas bullet, tipper | Rs 17,500 |
| Tractor | Rs 3,500 |
| Power tiller | Rs 3,000 |
| Auto rickshaw, three-wheeler, tempo | Rs 3,500 |
| Electric vehicle up to 50 kW | Rs 4,000 |
| Electric vehicle 51 to 125 kW | Rs 5,000 |
| Electric vehicle 126 to 200 kW | Rs 7,500 |
| Electric vehicle above 200 kW | Rs 9,500 |
| Electric e-rickshaw | Rs 3,500 |
| Two-wheeler | Rs 3,000 |
Frequently asked questions
What are the IRD tax rates for 2083/84?
For resident individuals: 1% up to Rs 10 lakh, 10% from Rs 10 to 15 lakh, 20% from Rs 15 to 25 lakh, 27% from Rs 25 to 40 lakh, and 29% above Rs 40 lakh. The same table applies to single persons and couples.
Is there a separate tax rate for married couples in 2083/84?
No. IRD’s sheet shows identical bands and identical tax for single and couple columns. On Rs 60 lakh of taxable income, both pay Rs 12,45,000.
How much can I deduct for my children’s school fees?
25% of the tuition fees you paid to a resident person for your children’s education, or Rs 25,000, whichever is lower.
What is the presumptive tax in Nepal for 2083/84?
For resident individuals with business income up to Rs 3 lakh and turnover up to Rs 30 lakh: Rs 7,500 in a metropolitan or sub-metropolitan city, Rs 4,000 in a municipality, and Rs 2,500 elsewhere.
How much tax is cut on YouTube income in Nepal?
5%, deducted by the bank, financial institution or money transfer company when it pays out foreign-currency income from uploading audio-visual content on social media, for individuals not running a registered business.
Conclusion
IRD’s official IRD tax rates 2083/84 sheet confirms one slab table for everyone, a Rs 10 lakh first band, a 29% top rate above Rs 40 lakh, and a full list of deductions, including the children’s tuition fee deduction of up to Rs 25,000. Small businesses pay a fixed Rs 2,500 to Rs 7,500 presumptive tax or turnover tax by band, and foreign-currency income from YouTube, freelancing and software is taxed at 5% at payout.
If you need help working out your tax, filing a D-01 or D-02 return, or claiming every deduction you are entitled to, Digital Solution can help.
Sources
- Inland Revenue Department, rate sheet: “आयकर ऐन, २०५८ अनुसार प्राकृतिक व्यक्तिको लागि लागू हुने करको दर (आय वर्ष २०८३/०८४ को लागि)” (6 pages)
- Inland Revenue Department website
- Digital Solution: Income tax rates in Nepal FY 2083/84
Tax law has conditions and exceptions not shown here. Check with IRD or a registered tax professional before you file.

Rabin Paudel
Rabin Paudel is the Founder of Digital Solution, a Content Creator, and an AI Trainer. He shares practical and easy-to-understand content on Artificial Intelligence, Digital Literacy, Online Services, FinTech, and Technology. His mission is to make technology simple, accessible, and useful for everyone.
View all posts by Rabin Paudel →