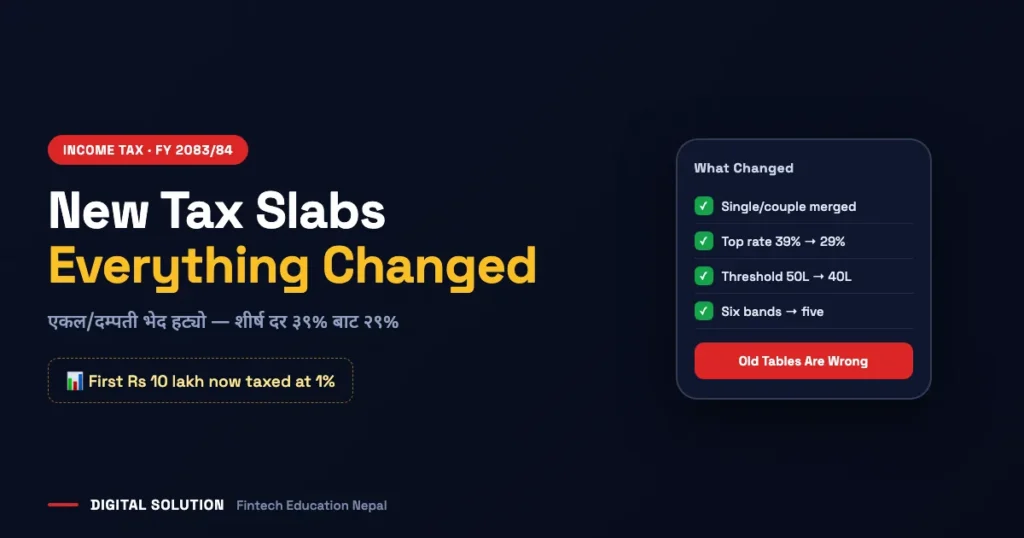
Nepal restructured its personal income tax this year, and the change is bigger than most people realise. The single-versus-couple distinction is gone, the top rate fell from 39% to 29%, and the threshold at which the top rate bites moved down from Rs 50 lakh to Rs 40 lakh. If you are budgeting from last year’s table, every number you have is wrong.
The FY 2083/84 Slabs
| Band | Slice of income | Rate | Tax on that slice | Cumulative tax |
|---|---|---|---|---|
| 1 | First Rs 10,00,000 | 1%* | Rs 10,000 | Rs 10,000 |
| 2 | Next Rs 5,00,000 | 10% | Rs 50,000 | Rs 60,000 |
| 3 | Next Rs 10,00,000 | 20% | Rs 2,00,000 | Rs 2,60,000 |
| 4 | Next Rs 15,00,000 | 27% | Rs 4,05,000 | Rs 6,65,000 |
| 5 | Above Rs 40,00,000 | 29%** | — | Rs 6,65,000 + 29% of excess |
* The 1% is the Social Security Tax, deposited to a separate revenue head. ** The 29% is the 27% rate plus two percentage points, on income above Rs 40 lakh.
What Changed From Last Year
| FY 2082/83 (old) | FY 2083/84 (now) | |
|---|---|---|
| Single vs couple tables | Two separate schedules | Abolished — one schedule |
| First band | Rs 5,00,000 (single) / Rs 6,00,000 (couple) @ 1% | Rs 10,00,000 @ 1% |
| Top rate | 39% | 29% |
| Top rate starts at | Rs 50,00,000 | Rs 40,00,000 |
| Number of bands | 6 | 5 |
Who Does Not Pay the 1% Social Security Tax
The 1% first-band charge is not universal. The Finance Bill, 2083 says the tax under that band does not apply to:
- a taxpayer registered as a sole proprietorship firm
- Pension income
- the income of an individual who contributes to a pension fund and the contribution-based Social Security Fund
Pension Income and Persons With Disabilities
The same section of the Bill sets two reductions that apply before the tax is worked out.
- Pension income. For a resident with pension income, an amount equal to 25% of the first band, which is Rs 2,50,000, is taken off taxable income, up to a limit to be prescribed.
- Persons with disabilities. For a resident with a disability, an extra amount equal to 50% of the first band, which is Rs 5,00,000, is taken off taxable income.
Worked Examples
Annual taxable income of Rs 8,00,000
Entirely inside band 1. Tax = Rs 8,000 (1%).
Annual taxable income of Rs 18,00,000
| Portion | Rate | Tax |
|---|---|---|
| First Rs 10,00,000 | 1% | Rs 10,000 |
| Next Rs 5,00,000 | 10% | Rs 50,000 |
| Remaining Rs 3,00,000 | 20% | Rs 60,000 |
| Total | Rs 1,20,000 |
Annual taxable income of Rs 50,00,000
Cumulative tax at Rs 40,00,000 is Rs 6,65,000. On the remaining Rs 10,00,000 at 29% that is Rs 2,90,000. Total Rs 9,55,000. Under last year’s schedule the same income attracted roughly Rs 14,65,000 — the difference is the point of the reform.
🤝 Not sure which band you fall into, or what you can deduct?
Send us your annual figures and we will walk you through the calculation for the current fiscal year. Digital Solution is not a tax firm — for filing and audit we will tell you when you need a registered practitioner.
One More Change Worth Knowing
Non-Residents
A non-resident individual is taxed at a flat 25%, unchanged from last year. Some specific activities carry their own rates — 5% for shipping, air transport, telecom, postal, satellite and optical-fibre services, 2% for those services provided within Nepal, and 5% on profit repatriation by a foreign permanent establishment.
Where These Figures Come From
Read in the Finance Bill, 2083. On 13 October 2026 we read section 57 of the Bill as published by the Ministry of Finance. It replaces section 1(1) of Schedule 1 of the Income Tax Act, 2058 with the five bands shown above, removes the separate schedule for couples, and carries the proviso on who does not pay the 1%. The running totals of Rs 10,000, Rs 60,000 and Rs 2,60,000 are written into the Bill’s text.
One limit remains. The Bill is the text presented with the budget. The Finance Act was gazetted on Ashadh 30, 2083 (around 15 July 2026), and we have still not opened Schedule 1 of the gazetted Act itself. A professional firm’s published summary of the enacted rates shows the same bands, so the two sources agree. For a filing decision, confirm with IRD or a registered tax practitioner.
Frequently Asked Questions
What is the income tax rate in Nepal for FY 2083/84?
1% on the first Rs 10 lakh, 10% on the next Rs 5 lakh, 20% on the next Rs 10 lakh, 27% on the next Rs 15 lakh, and 29% above Rs 40 lakh.
Is there still a separate rate for married couples?
No. The single and couple schedules were merged into one for FY 2083/84.
What happened to the 36% and 39% bands?
They are gone. The top rate is now 29%, starting from Rs 40 lakh instead of Rs 50 lakh.
What is the 1% on the first band?
Social Security Tax, deposited to a separate revenue head. Under the Finance Bill, 2083 it does not apply to a taxpayer registered as a sole proprietorship firm, to pension income, or to the income of an individual who contributes to a pension fund and the contribution-based Social Security Fund.
Are SSF contributors exempt from the 1%?
Yes, according to the Finance Bill, 2083. Its proviso says the first-band tax does not apply to the income of an individual who contributes to a pension fund and the contribution-based Social Security Fund. Check that your payslip reflects it.
What is the rate for non-residents?
A flat 25%, with specific lower rates for certain transport and telecommunications activities.
How much tax on Rs 10 lakh income?
Rs 10,000, if the whole amount is taxable income and the 1% band applies to you.
Is this on gross salary or after deductions?
On taxable income — after allowable deductions such as retirement contributions and insurance premium. Calculate the deductions first.
Sources
- Ministry of Finance, Finance Bill, 2083 (आर्थिक विधेयक, २०८३), section 57, amendment to Schedule 1 of the Income Tax Act, 2058, read 13 October 2026: mof.gov.np.
- Finance Act 2083 (आर्थिक ऐन २०८३), gazetted Ashadh 30, 2083, listed as the current Finance Act by the Inland Revenue Department. Schedule 1 of the gazetted Act was not retrieved directly.
- PKF T.R. Upadhya & Co., published tax rate summary for the year, cross-checked against multiple independent secondary sources.
Related Reading
- PAN and VAT registration in Nepal
- Freelancer payment and tax guide
- Social Security Fund: complete guide
Disclaimer: Digital Solution Nepal is an independent educational and digital-service assistance website — not a tax authority, not a chartered accountancy firm and not a law firm. Tax rates and thresholds change with every Finance Act, and individual circumstances differ. Nothing here is tax advice — the Inland Revenue Department, the current Finance Act and a registered tax practitioner are final. Verify before filing or paying.

Rabin Paudel
Rabin Paudel is the Founder of Digital Solution, a Content Creator, and an AI Trainer. He shares practical and easy-to-understand content on Artificial Intelligence, Digital Literacy, Online Services, FinTech, and Technology. His mission is to make technology simple, accessible, and useful for everyone.
View all posts by Rabin Paudel →