Updated August 2026. Fines below are set in the Companies Act 2063 and are statutory rather than annual-budget figures. We found no evidence they were amended for FY 2083/84, but could not confirm that either.
Thousands of Nepali companies are quietly accumulating fines right now. Not because anyone did anything wrong — because nobody filed the annual return, the penalty compounds every year, and it is charged to the directors personally, not just to the company.
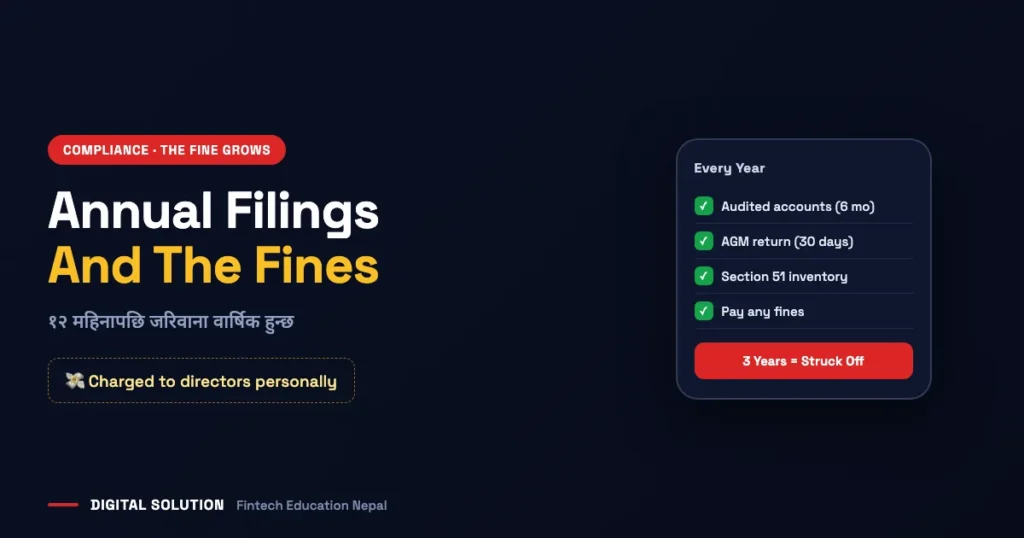
What You Must File Every Year
| Filing | Deadline | Provision |
|---|---|---|
| Audited annual financial statements with the auditor’s report | Within 6 months of fiscal-year end — so by end of Poush for a Shrawan–Asar year | s.80(2) |
| Return of the AGM, attendance, financial statements, board report, auditor’s report and resolutions | Within 30 days of the AGM | s.80(1) |
| Inventory of shareholders, capital, bank loans and current directors | Prepared as at 30 days before the AGM; filed within 30 days after it. A company holding no AGM: within one year of registration | s.51 |
| Any alteration to those particulars — new director, share transfer, address | Within 6 months of the alteration | s.51 |
The Penalty Table
This is the figure the whole article exists for. The fine escalates on two axes at once — how late you are, and your paid-up capital (not authorised capital):
| How late | Paid-up up to Rs 25 lakh | Up to Rs 1 crore | Above Rs 1 crore |
|---|---|---|---|
| Up to 3 months | Rs 1,000 | Rs 2,000 | Rs 5,000 |
| 3 to 6 months | Rs 1,500 | Rs 3,000 | Rs 7,000 |
| 6 to 12 months | Rs 2,500 | Rs 5,000 | Rs 10,000 |
| Beyond 12 months | Rs 5,000 per year | Rs 10,000 per year | Rs 20,000 per year |
What Happens If You Keep Ignoring It
| Stage | What occurs |
|---|---|
| Three consecutive financial years of not filing under s.80 or not paying fines under s.81 | The Registrar may move to cancel your registration |
| Notice | Written notice to your registered address plus publication in a national daily |
| Your window to object | Two months, in writing |
| If you do not respond | Registration is cancelled |
⚠ Cancellation is not a clean escape — this is the part owners get wrong.
- Existing liabilities remain enforceable against officers and shareholders personally. The company disappearing does not take the debts with it.
- Assets devolve on the shareholders proportionally.
- The company name cannot be reused.
People let a company lapse believing it quietly dissolves. It does not — it leaves them personally exposed with no entity to stand behind.
A restoration provision exists in the Act for cancelled companies, but we could not retrieve its text — grounds, procedure and any time limit are unverified. If you need to revive a struck-off company, that is a question for a professional, not an article.
🤝 Company behind on filings and unsure how much has built up?
Tell us your company type, paid-up capital and roughly how long since the last filing. Digital Solution will help you map what is outstanding and in what order to fix it — and tell you plainly when you need an auditor or a company lawyer.
Does a Private Company Need an AGM?
Yes, a Dormant Company Still Files
A company with no transactions is not exempt. The strike-off trigger is failure to file — there is no carve-out for zero activity, and the Act expressly contemplates companies that hold no AGM.
The Tax Connection
Company compliance and tax compliance are separate systems, but they meet at one point that matters: a tax clearance certificate is required to close a company, and the Inland Revenue Department will not issue one while income tax, VAT or TDS returns are outstanding.
On Penalty Waivers — Do Not Count on One
Separately, the Finance Act 2083 created tax settlement windows — principal plus 1% with interest and penalties waived. That is an Inland Revenue amnesty, not a Company Registrar one. Do not conflate the two, and do not delay filing in the hope of a discount that may not exist.
Getting Current: The Order to Do It In
- Find out exactly what is outstanding — which years, which filings, and your paid-up capital band.
- Get the accounts audited for every missing year. This is the long pole and usually the largest cost.
- Pass and document the approving resolution for each year.
- File the section 51 particulars, including any director or shareholding changes you never reported.
- Pay the fines — they must be cleared, and they grow while you deliberate.
- Then decide: keep the company current going forward, or close it properly.
Frequently Asked Questions
What must a private limited company file every year in Nepal?
Audited financial statements with the auditor’s report within six months of fiscal-year end, the AGM return within 30 days of the meeting, and the section 51 inventory of shareholders, capital and directors.
What is the penalty for not filing the annual return?
It scales with delay and paid-up capital, from Rs 1,000 up to Rs 20,000 — and beyond twelve months it becomes an annual charge of Rs 5,000, Rs 10,000 or Rs 20,000 depending on capital.
Who pays the fine — the company or the director?
It is imposed on the director or officer in default.
Can the Registrar cancel my company?
Yes, after three consecutive financial years of not filing or not paying fines, following notice and publication, with two months to object.
If my company is struck off, do the debts disappear?
No. Liabilities remain enforceable against officers and shareholders personally, and the name cannot be reused.
Does a dormant company still have to file?
Yes. There is no exemption for having no transactions.
Must a private company hold an AGM?
Contested. The filing obligations apply either way — pass and file a resolution approving the audited accounts within six months of year end, and check your articles.
Is there a penalty waiver available now?
Do not assume so. A previous scheme was halted by an interim court order and we could not confirm the current position.
Sources
- Companies Act 2063 — sections 51, 76, 80, 81, 136 and 166, via published consolidated text.
- Reporting on the 2081 penalty-waiver ordinance and the subsequent interim court order.
- Finance Act 2083 tax settlement windows as described in professional summaries — noted as distinct from Registrar penalties.
Related Reading
- Tax clearance certificate: who needs it and how to get one
- Filing your income tax return online
- VAT return filing: deadlines and penalties
Disclaimer: Digital Solution Nepal is an independent educational and digital-service assistance website — not a government office, not a law firm and not an audit firm. Registration procedures, fees and thresholds change through Acts, regulations and local Economic Acts, and requirements differ by office, sector and province. Nothing here is legal or professional advice — the relevant registering office and a qualified professional are final. Confirm before filing or paying anything.

Rabin Paudel
Rabin Paudel is the Founder of Digital Solution, a Content Creator, and an AI Trainer. He shares practical and easy-to-understand content on Artificial Intelligence, Digital Literacy, Online Services, FinTech, and Technology. His mission is to make technology simple, accessible, and useful for everyone.
View all posts by Rabin Paudel →